Metrics library
- Realized cap: valuing coins at the price they last moved
- Realized price: the average price coins last moved at
- MVRV ratio: market value compared with realized value
- NVT ratio: network value compared with on-chain volume
- NUPL: how much paper profit or loss the network holds
- SOPR: are coins being spent at a profit or a loss?
- Percent supply in profit: how many coins are above water
- HODL waves: reading Bitcoin’s supply by coin age
- Coin Days Destroyed: measuring when old bitcoin starts to move
- Hash rate: how much work is securing Bitcoin
- Active addresses: counting who used the chain — roughly
- Puell Multiple: is miner income high or low compared with the past year?
- Exchange netflow: coins in minus coins out
- Stablecoin supply ratio (SSR): Bitcoin’s size against the stablecoin pile
- Funding rate: the price of staying long or short in perpetual futures
- Open interest: how much leveraged exposure is open right now
Funding rate: the price of staying long or short in perpetual futures
The funding rate is the percentage that holders of perpetual futures pay each other at regular intervals. Charted over time, it shows which side of the derivatives market has been paying to stay in.
Photo: “Interest Rates” by 401(K) 2013, CC BY-SA 2.0, via Flickr (edited: cropped and resized).
The funding rate is the periodic payment between longs and shorts in a perpetual futures market. When the perp trades above spot it is positive and longs pay shorts; below spot it is negative and shorts pay longs [1]. Glassnode and others publish it as a futures metric [2].
Key points
- 1Funding measures who pays whom to hold perpetual futures, and how much, per interval.
- 2Positive funding: perps trade above spot and longs pay. Negative funding: perps trade below spot and shorts pay.
- 3Rates are quoted per interval (for example per 8 hours or per hour), so convert before comparing venues.
- 4Aggregated funding charts mix many venues with different rules; read the provider’s methodology.
- 5Funding describes positioning. It is not a price forecast.
What does the funding rate measure?#
Perpetual futures are derivatives with no expiry date, so they need another way to stay close to the price of the underlying coin. That way is funding: “a periodic fee that is paid by one side of the contract (either long or short) to the other side” [1]. The funding rate is that fee expressed as a percentage of the position’s value for one interval.
The sign tells you the direction. If the contract’s price is higher than the spot price, funding is positive and longs pay shorts; if it is lower, funding is negative and shorts pay longs [1]. On venues that document it this way, funding passes between traders and the venue collects no fee on it [1]. For the full mechanics, read perpetual futures and funding rates.
How is the funding rate calculated?#
Each venue publishes its own formula. A common structure, shown here using Hyperliquid’s documentation as one example, adds a premium (how far the perp trades from the spot oracle price) to a small interest component, with a clamp limiting how far the interest part can pull the result: Funding = average premium + clamp(interest − average premium, −0.05%, +0.05%) [1]. The interest component there is fixed at 0.01% per 8 hours, and the rate is capped at 4% per hour [1]. Bybit documents the same premium-plus-clamped-interest core, then clamps the result again between upper and lower limits that, under normal conditions, come from each contract’s margin rates [3].
Funding payment = Position size × Oracle price × Funding rate (per interval)Hyperliquid uses the spot oracle price, not the mark price, to value the position for this payment [1]. Other venues may define the price and interval differently.
How do you compare funding rates across venues?#
A funding rate is meaningless without its interval. Hyperliquid computes an 8-hour rate but pays one-eighth of it every hour [1]. Bybit’s help page uses an 8-hour interval as its example, but switches a contract to hourly settlement when its funding rate reaches the preset limit [3]. So intervals differ between venues and can even change within one venue. Before comparing, convert every rate to the same period.
| Step | Value |
|---|---|
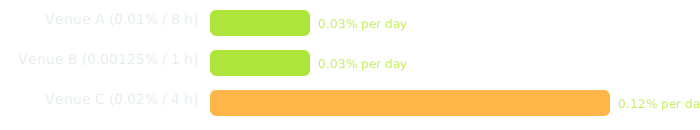
| Venue A: 0.01% per 8 hours × 3 | 0.03% per day |
| Venue B: 0.00125% per 1 hour × 24 | 0.03% per day |
| Venue C: 0.02% per 4 hours × 6 | 0.12% per day |
| Venue C expressed per 8 hours | 0.04% (four times Venue A) |
| Venue A over 365 days, simple sum | 10.95% |
| Venue C over 365 days, simple sum | 43.8% |
| Daily cost on a $10,000 position at Venue C | $12 |
Venue B’s rate looks eight times smaller than Venue A’s, yet the daily cost is identical. Annualised figures assume the rate stays constant all year, which it never does — use them only to compare, not to predict.
The three quotes converted to a daily rate
How do data providers build a funding-rate chart?#
Funding happens venue by venue, so any market-wide chart is an aggregate built by a data provider. Glassnode, for example, lists funding rate among its futures metrics alongside open interest, volume, basis and liquidations, updated every 10 minutes with a nightly backfill to fill gaps [2]. It also warns that off-chain data such as a single exchange’s perpetual futures positions can arrive late [4], so the latest point on a chart may still change.
Before trusting an aggregate, ask: which venues are included, how is each one converted to a common interval, and is the average weighted by open interest or simply averaged? Two charts called “funding rate” can disagree for these reasons alone.
How do analysts read the funding rate?#
| What you see | Reasonable reading | What it does not tell you |
|---|---|---|
| Small positive funding | Often just the venue’s baseline interest component; perps close to spot | That traders are especially bullish |
| High positive funding for days | Longs keep paying to stay in; positioning is crowded on the long side | When or whether price will fall |
| Negative funding | Perps below spot; shorts are paying to stay in | That price has bottomed |
| Funding differs a lot between venues | Different users, rules or liquidity on each venue | A free profit — moving money between venues has costs and risks |
What are the limits of funding-rate data?#
- It covers perpetuals only. Spot markets and dated futures have no funding.
- It is venue-specific. Caps, intervals and premium measures differ; Hyperliquid describes its cap as “much less aggressive” than those of centralized exchanges [1]. Bybit says updates to its funding limits and settlement frequencies are made dynamically, without separate announcements [3].
- It reflects leveraged traders. Funding says nothing about long-term holders who buy spot and never touch derivatives.
- Recent values can be revised. Late-reported venue data can change the most recent points [4].
Funding rate in one box
- Measures
- Periodic payment between longs and shorts in perpetual futures
- Positive sign means
- Longs pay shorts [1]
- Example baseline (Hyperliquid)
- 0.01% per 8 hours interest component [1]
- Example payment frequency (Hyperliquid)
- Every hour [1]
- Example interval (Bybit)
- 8 hours in its help page; hourly when funding hits its limit [3]
- Aggregated chart update cadence (Glassnode)
- Every 10 minutes [2]
What mistakes do beginners make here?#
- Comparing rates with different intervals
Always convert to the same period first. An hourly rate and an 8-hour rate are not comparable as quoted.
- Reading funding as the cost of a trade
Funding is a recurring cost or income for as long as you hold. A small rate becomes a large sum over weeks — and grows with leverage.
- Treating high funding as a short signal
It shows which side is crowded, not when the crowd leaves.
- Ignoring how the aggregate is built
Which venues, which weighting, which interval conversion — these choices can change the chart more than the market does.
Frequently asked questions#
Is a positive funding rate good or bad?
Neither. It means longs are paying shorts because the perpetual trades above spot [1]. Whether that matters depends on your position and how long it persists.
Why is funding often exactly the same small number?
On venues with an interest component and a clamp, any small premium is cancelled out and funding settles on the baseline — 0.01% per 8 hours on Hyperliquid [1].
Where can I see funding rates?
Each derivatives venue shows its own funding rate. Data providers publish aggregates; check their methodology before comparing.
Does funding affect spot holders?
Not directly. Only holders of perpetual positions pay or receive it.
The bottom line#
The funding rate is the clearest single number for who is paying to stay leveraged in perpetual futures. Read it with its interval, its venue and its sign, and remember it describes positioning rather than predicting price.
Pair it with open interest to see how much positioning exists, and with open interest and liquidations to understand how quickly that positioning can unwind.
Sources#
Grade A = primary source (regulator, protocol specification, client code, original author). Grade B = expert secondary source used for explanation only.
- AHyperliquid Docs. Funding, 2026. Used as one example of how a venue documents funding; other venues differ.
- BGlassnode Docs. Datapoint Finalization, 2026.
- ABybit Help Center. Introduction to Funding Rate, 2026. Bybit’s own rules for its own contracts (page last updated 2026-05-22); not a statement about other venues.
- BGlassnode Docs. Point-in-Time Metrics, 2026.
- AEuropean Supervisory Authorities (EBA, ESMA, EIOPA). EU financial regulators warn consumers on the risks of crypto-assets, 2022.